Lately, hospitals and health systems around the country are receiving ineligibility determinations from FEMA denying or reducing otherwise eligible Public Assistance funding for COVID-19 medical care claims. FEMA asserts in these determinations that the denied funding would be a prohibited duplication of benefits (DOB) because the costs are already covered by patient care revenue. While reducing claims for DOB with patient care revenue is consistent with limitations on FEMA's Stafford Act authority, applicants for Public Assistance should pay close attention to these denials. Baker Donelson's Disaster Recovery and Government Services team has seen multiple instances where FEMA applied double DOB reductions, resulting in the erroneous denial of millions in eligible Public Assistance funds. This Disaster Recovery Brief explains the process that leads to the error, how to identify the problem, and how to bring it to FEMA's attention.
Understanding the Process To Understand the Problem
The extraordinary burden on emergency responders, including medical care providers, to protect public health and safety from COVID-19 resulted in an unprecedented nationwide set of Stafford Act major disaster declarations. Those declarations provided access to Public Assistance grant funds for certain medical care and safe opening and operating costs.
FEMA is prohibited from duplicating financial assistance received from any other source, and usually applies estimated and actual insurance proceeds to reduce the cost of physical construction projects to avoid a prohibited DOB. But the cost of medical care is typically considered ineligible for Public Assistance. This is because the U.S. health care system can typically respond to and recover from the medical demands of a declared event through the private and public-funded American health insurance system. The duration and scope of COVID-19, however, resulted in extraordinary costs that were not covered by insurance. This required FEMA to develop processes for avoiding a DOB with patient care revenue in Public Assistance grants for medical care.
FEMA first asked medical providers for suggestions to avoid a DOB and then engaged the RAND Corporation to help devise a uniform methodology. It quickly became apparent that there is no single way that all medical providers account for patient care revenue within their diverse health systems. So, FEMA took a two-phased approach. It encouraged applicants to submit their own methodology with their claims, and developed an optional Standard Methodology to speed agency review and establish a system that the agency could use if it rejected the applicant's proposed methodology.
How To Identify the Problem
Many applicants provided proposed methodologies and applied those methodologies to their claimed amounts to calculate an applicant-proposed DOB reduction. Those applicant-proposed methodologies were reviewed by RAND, resulting in recommendations to FEMA, which the agency typically accepted. Many were deemed reasonable and moved through to obligation. But many were found unreasonable.
If FEMA rejected the applicant's methodology and FEMA and the applicant were unable to revise the applicant's methodology to meet FEMA's approval, then FEMA had RAND apply the agency's Standard Methodology. The Standard Methodology uses pre-COVID (calendar year 2019) revenues and expenses from the applicant's audited financial statements to create baseline cost and revenue figures that serve as an allowable ceiling on claimed costs. In simplified terms, the Standard Methodology compares an applicant's pre-pandemic revenues and expenses to pandemic-period revenues and expenses to determine whether patient care revenue likely compensated the applicant for costs that FEMA would otherwise reimburse. FEMA only reimburses eligible costs that exceed the amount of patient care revenue it would normally expect to receive for the type of cost at issue. The formula looks like this (PCR stands for Patient Care Revenue):
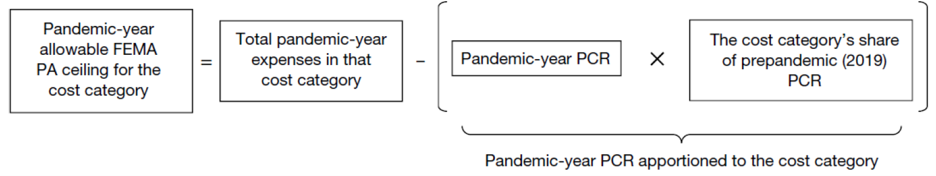
The double DOB problem arose because RAND did not realize that applicants often submitted both their total eligible costs and a proposed DOB-adjusted amount that reflected the reduction they believed FEMA should apply. RAND often used the applicant's proposed DOB-reduced amount as the total claimed amount when applying FEMA's Standard Methodology to reduce the claim for DOB. Because the applicant's proposed reduction had already accounted for a DOB with patient care revenue, applying FEMA's ceiling calculation to that already-reduced figure effectively deducted the same revenue twice.
The problem is not immediately obvious when looking at a FEMA determination memorandum denying costs for DOB. The determination memorandum will identify the claimed amount and the amount of the proposed reduction. But applicants need to look back at the amount of the incurred costs submitted with their claim – before their proposed DOB reduction – and make sure that number matches the claimed amount on the determination memorandum. If it does not – FEMA likely made an erroneous double DOB reduction.
For example: If an applicant incurred $100 million in eligible costs and proposed a $20 million DOB reduction, its reduced claim would be $80 million. If FEMA then incorrectly treats the $80 million figure as the starting point and applies a $30 million reduction through the Standard Methodology, the applicant effectively receives a $50 million reduction instead of a $30 million reduction.
How To Bring It to FEMA's Attention
We have seen many COVID-19 double DOB reductions recently. For example, one state entity submitted a proposed methodology that was rejected. Instead of trying to revise its methodology, the applicant appealed and recalculated its DOB reduction using FEMA's Standard Methodology.
This applicant's audited financial statements were organized on a July – June fiscal year basis. To ensure that COVID-19 costs were not included in the pre-pandemic baseline figures, we used the applicant's monthly financial statements to capture only January – December revenues and expenses. To isolate January – December 2019 financials, it was necessary to use monthly financial statements to reconstruct true pre-pandemic calendar year 2019 revenue and expense figures. Those accurate figures were then used to calculate a pre-pandemic baseline, which was used to calculate calendar year allowable ceilings by cost type, consistent with FEMA's Standard Methodology. The applicant's actual claim amounts (without the reduction it originally proposed and FEMA rejected), allocated by cost type (labor, supplies and services, and equipment) and year (by date the work was performed or supply/service/equipment used), were then applied to the properly calculated allowable ceilings. Claim amounts that exceeded the allowable ceiling were considered to be duplicated by patient care revenue, consistent with FEMA's Standard Methodology.
By fixing the baseline calculation to exclude impacts from COVID-19, properly categorizing costs by type and calendar year they were incurred, and reversing the double duplication error, this applicant successfully recovered roughly $23 million more than it would have had it not challenged the agency's reduction.
Practical Considerations
Because FEMA's COVID-19 medical care DOB analysis is applied to all of an applicant's projects, for COVID-19 DOB appeals, FEMA requires applicants to appeal every project.
Applicants always bear the burden of proof. Appeals must be factually supported, consistent with law and policy, and persuasive. In support of its appeal, the applicant discussed in this example submitted all applicable audited annual reports and the monthly data that provided the basis for the annual reports. The applicant also had its original detailed claim spreadsheets backed by dated invoices and timesheets showing the date and description of the costs. They also provided extensive legal analysis explaining why its calculations and results are consistent with agency policy.
The growing number of apparent double DOB reductions demonstrates that even sophisticated FEMA review processes can produce significant errors with substantial financial consequences. After receiving a determination memo from FEMA (for COVID-19 or any disaster), applicants should carefully examine the agency's methodology, underlying financial assumptions, and application of law and policy. Experienced counsel can help evaluate the decision, identify appealable issues, develop the evidentiary record, and develop the clear and persuasive appeal needed to maximize recovery.
For questions about FEMA's Public Assistance program, compliance issues, or help with an unfavorable denial of assistance, please contact Erin Greten, Michelle Zaltsberg, or any member of our Government Solutions and Public Funding Group.